Water backup guide
Does Homeowners Insurance Cover Sewer Backup?
Water coming up the drain is not the same as water coming in the door.
Last updated: September 26, 2026
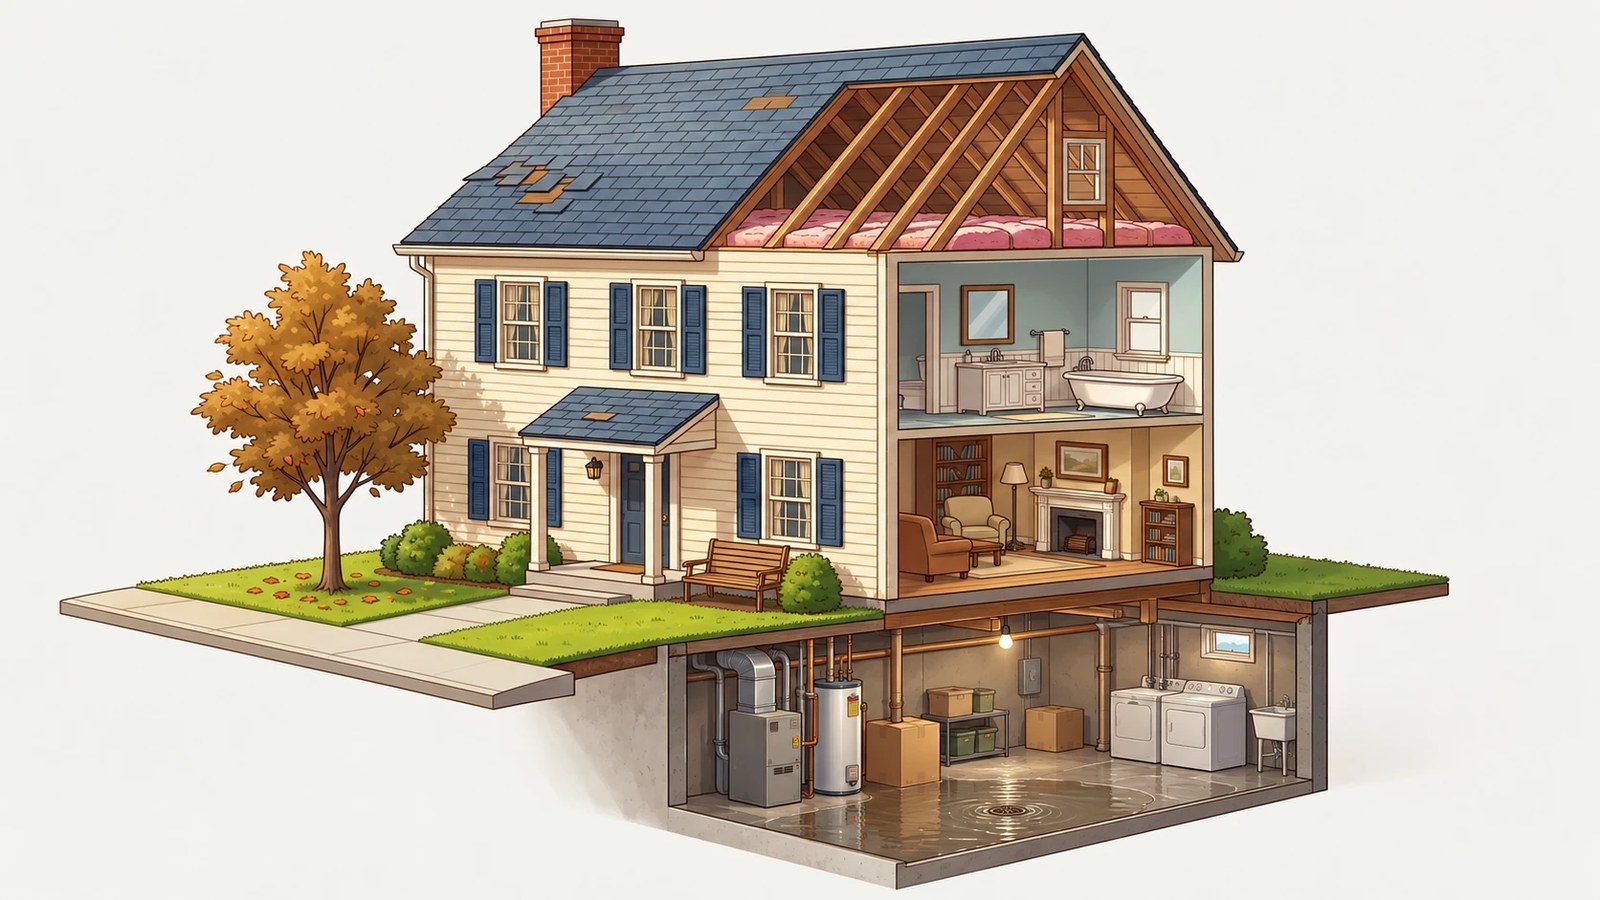
Most standard homeowners policies exclude water that backs up through sewers, drains, or a sump pump. Coverage for it is usually added separately, as an endorsement, and often with a small limit.
Your policy's exact wording controls. Use this page to know what to look for, then confirm with your licensed agent.
What "backup" usually means
- Sewage or water pushing up through a floor drain, toilet, tub, or sink.
- A sump pump that fails or loses power and the pit overflows.
- A blocked municipal sewer line sending water back toward the house.
Water that starts in the pipes and comes up into the house.
What it usually is not
- Rain or groundwater seeping through basement walls or the floor (most policies treat that as flood or seepage and exclude it).
- A pipe bursting inside the house (handled under different wording, often covered when sudden).
- A backup caused by an outside flood (most policies call that flood, even though it arrived through the drain).
Same wet basement, three different answers. The wording decides.
Why it matters
A backup ruins a finished basement in an afternoon: flooring, drywall, the furnace, the washer and dryer, everything stored down there. Cleanup alone is often several thousand dollars because sewage requires professional remediation.
Endorsement limits are commonly $5,000 to $25,000, and some policies cap the endorsement well below what a finished basement costs to restore.
Where to find it in your policy
Policy wording
Look under Optional Coverages or Forms and Endorsements on your declarations page for the words water backup, sewer, drain, or sump. If nothing like that appears, the standard exclusion in the policy booklet most likely applies.
How to read what you have
Find the limit
The endorsement usually has its own dollar limit, separate from your belongings limit. On many forms that number is the most the policy pays for a backup, structure and contents combined.
Check what it excludes
Even with the endorsement, most versions still exclude backup caused by flood or surface water, and some exclude the sump pump itself.
Check the deductible
Some endorsements use the regular deductible; some have their own. The declarations page or the form says which.
Renters and condo owners
Renters policies often offer the same endorsement for belongings. In a condo, the association's master policy may or may not respond to a backup in your unit; who pays for what is set by the association documents and your own policy. Ask both.
Questions for your agent
- 1Does my policy include a water or sewer backup endorsement, and where is it listed?
- 2What is the limit, does it cover both the structure and my belongings, and which deductible applies?
- 3What does the endorsement still exclude, and would a backup caused by heavy rain be treated as flood?
CoverageDecoder finds the backup wording in your policy, quotes the page, and explains what the limit and exclusions mean for your house.
Keep reading
Sources for review: Insurance Information Institute, "Water backup and sump pump overflow coverage"; sample endorsement wording from a Travelers HQ-208 (MD) form. Sources are for review and general education.
Want this checked against your own answers?
That is how these policies usually work in general. What matters is what yours says. The report is built from your answers about your home and walks through the topics they point to. Upload your own policy document and it also shows you what it found, with no insurance jargon. One price, $9.
No app to download. No subscription. One report, one price.
CoverageDecoder is an educational tool, not insurance advice. For decisions about your coverage, talk with your licensed insurance agent.